• Cgeldert@shaw.ca
(403) 620-8534
Christopher Geldert, CA
  • HOME
  • ABOUT
    • ABOUT
    • SUPPLIERS
    • RESOURCES
    • PRIVACY & TERMS
  • SERVICES
    • INSURANCE PLANNING
      • LIFE INSURANCE
      • MORTGAGE LIFE INSURANCE
      • DISABILITY INSURANCE
      • CRITICAL ILLNESS INSURANCE
      • HEALTH & DENTAL
    • FAMILIES
      • ESTATE PLANNING
      • ESTATE PLANNING FOR MATURE FAMILIES & RETIREES
      • INSURANCE PLANNING
    • BUSINESS OWNERS
      • INSURANCE PLANNING
      • ESTATE PLANNING
  • CONTACT
  • LATEST NEWS
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu

Supporting Your Aging Parents Without Sacrificing Your Own Stability

Blog, Estate Planning, Retirees, Retirement

Supporting Your Aging Parents Without Sacrificing Your Own Stability

It starts gradually. A missed bill here. A forgotten appointment there. Then one day you realize your parents may no longer be able to manage everything on their own. You want to help—but you also have a job, a family, and your own responsibilities. For many adults, stepping in to support aging parents financially or emotionally is one of the most challenging roles they’ll take on.

As life expectancy increases, more Canadians are finding themselves caring for elderly parents while still raising children or building their own future. The emotional weight is one thing—but the financial implications and paperwork can feel overwhelming. The good news? With thoughtful preparation and open communication, you can protect your loved ones while staying grounded yourself.

Start with Honest, Compassionate Conversations

Talking about money, health, or legal documents with your parents isn’t easy. Many people avoid these topics because they’re uncomfortable or feel “too personal.” But waiting until there’s a crisis—like a fall, hospitalization, or memory loss—can limit your options and lead to rushed decisions.

Start with small, respectful conversations. Ask your parents what they would like help with, and offer to support them in ways that don’t feel intrusive. Share a story about someone else who went through this—it can make the conversation feel less like a confrontation and more like a shared concern.

If you have siblings, try to align with them first. It’s helpful to present a united and supportive front, even if only one person is taking the lead. Having an agreed-upon approach can also reduce misunderstandings or resentment down the line.

Gather the Right Information Early

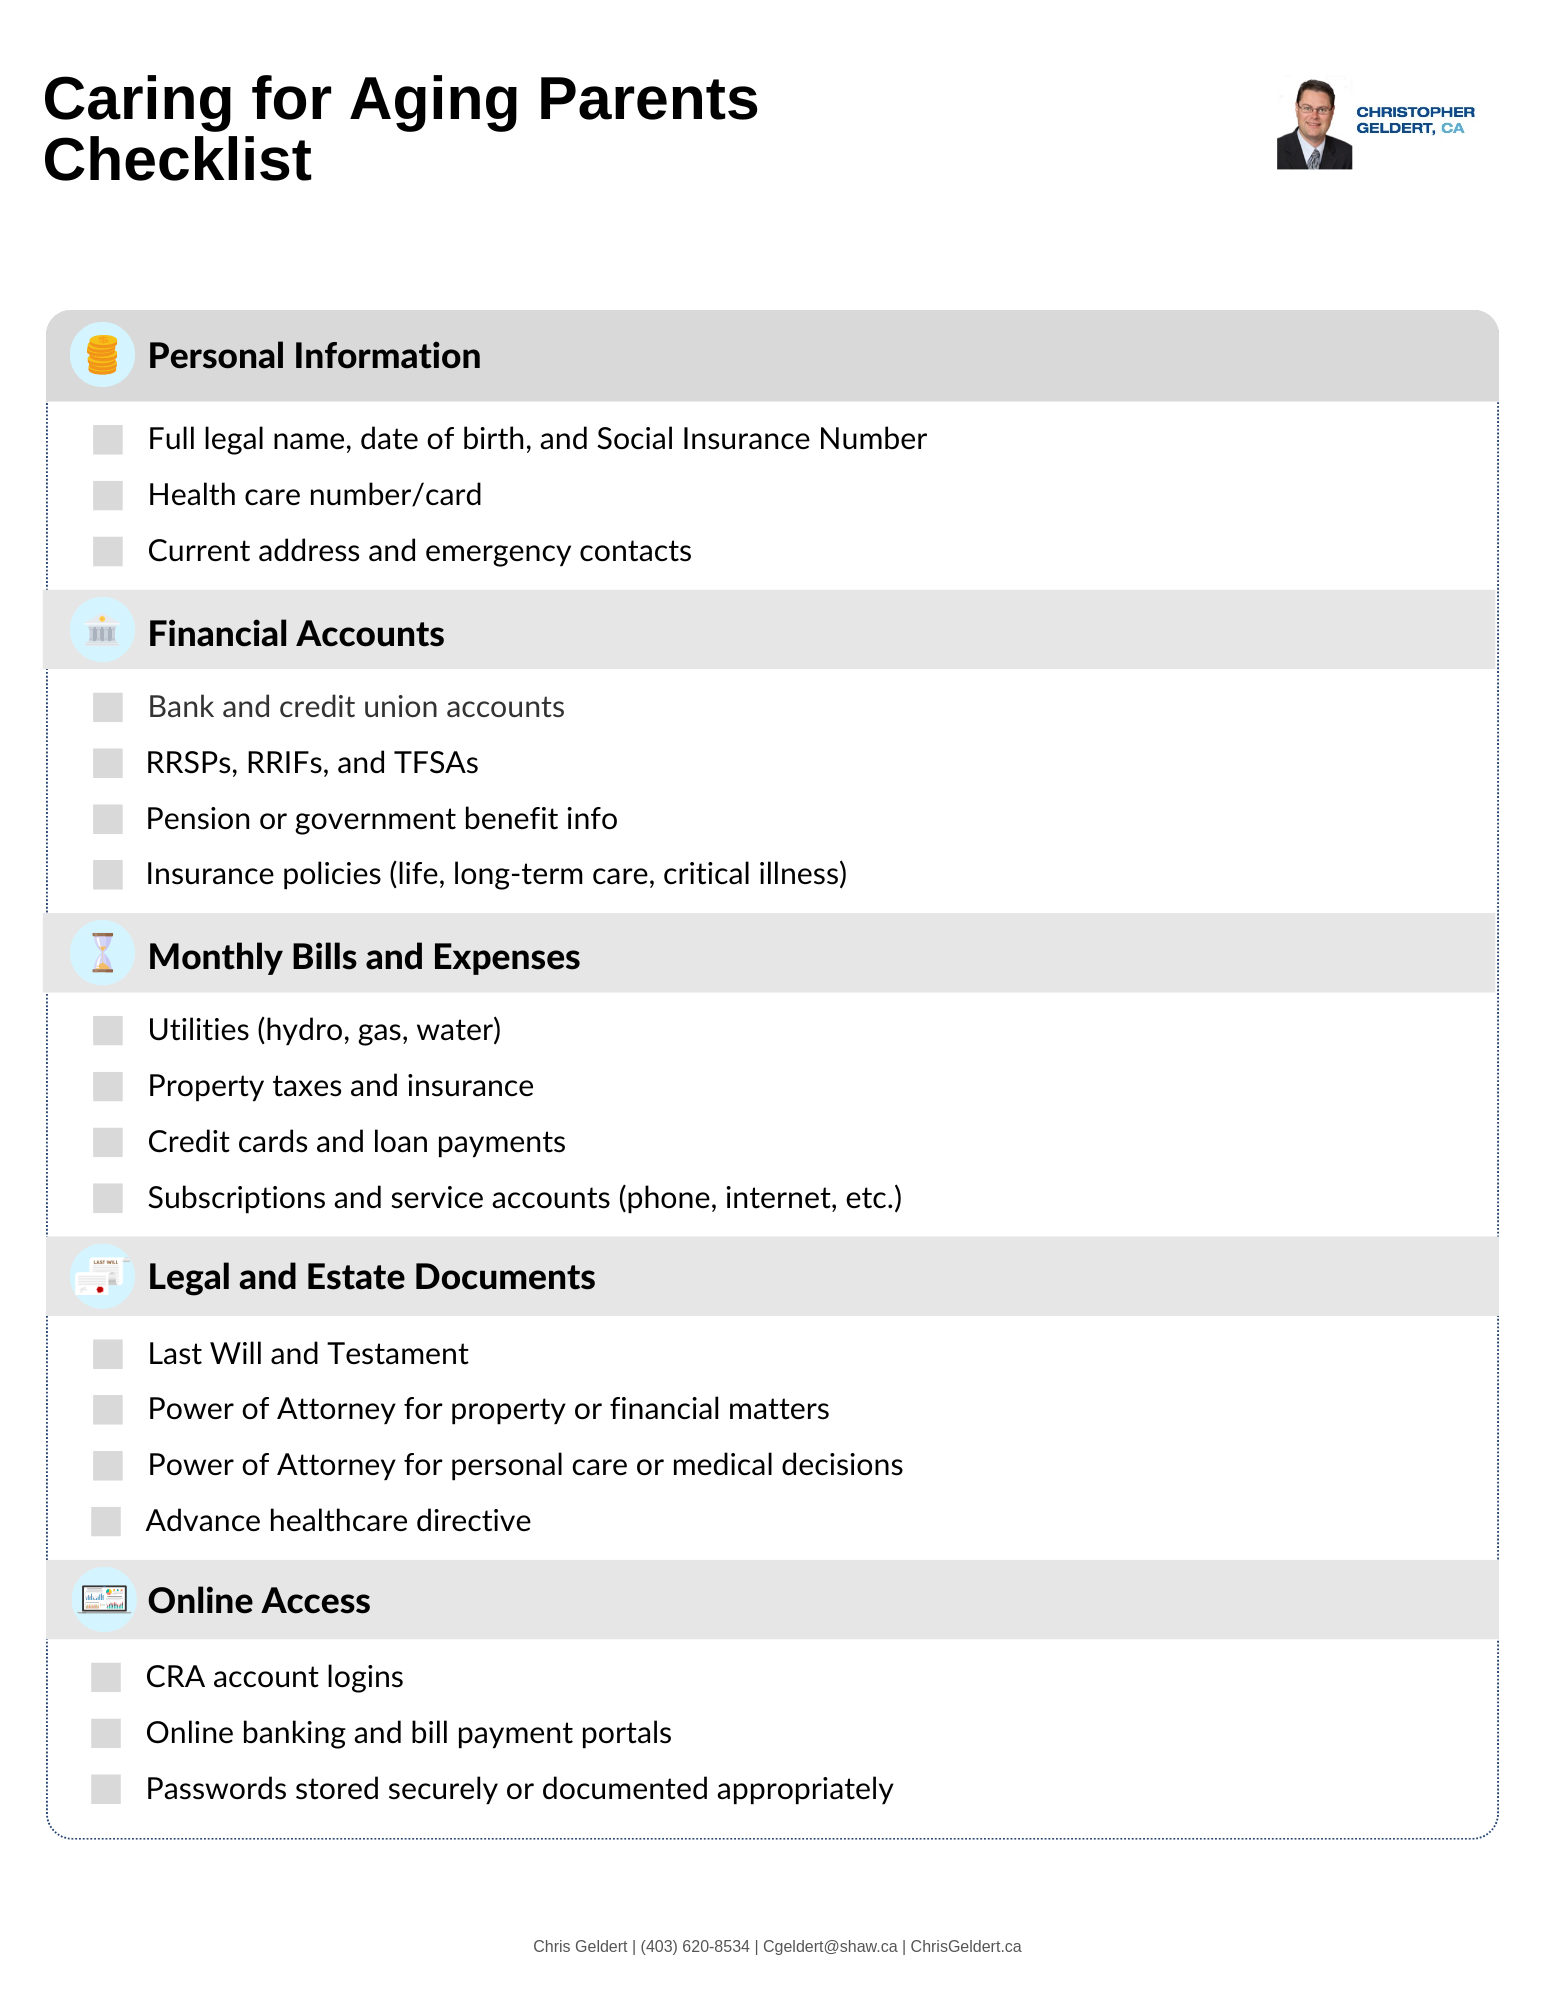
One of the best things you can do is help your parents create an “Information Checklist.” This isn’t just about knowing where their money is—it’s about understanding the full picture of their finances, obligations, and preferences.

Here are some items to include in that checklist:

  • Personal information: Social Insurance Number, health care card, date of birth, current address, emergency contacts
  • Financial accounts: bank accounts, insurance policies, pensions, RRSPs/RRIFs, TFSAs
  • List of monthly bills: utilities, credit cards, insurance premiums, phone, internet, property tax
  • Legal documents: will, power of attorney (financial and medical), healthcare directive, deeds or titles
  • Login credentials (if possible): online banking, CRA account, utility portals
  • Health records: medication list, primary doctor, pharmacy, care history

Organize everything into one place—either a binder, secure folder, or encrypted digital file. The goal isn’t to take control right away—it’s to be ready if and when it’s needed
brandableContent

Understand the Legal Side of Helping

Even if your parents trust you to step in, you can’t simply start managing their accounts without legal authority. A power of attorney (POA) document gives you the right to act on their behalf for financial and/or medical matters. This must be signed while your parent is mentally capable.

If you already have POA documents in place, don’t stop there. Reach out to their bank, insurance company, and investment firm to confirm they accept the documents—or if they require their own internal forms. Some institutions may ask for a doctor’s letter confirming incapacity before they will recognize the POA.

Also consider notifying government agencies like Service Canada or provincial health bodies if you have POA status. It can take time for your authority to be processed, so doing it in advance saves delays later.

Without a valid POA, you may need to apply for guardianship or trusteeship through the courts, which can be a lengthy and stressful process.

Create a Plan—And Keep It Flexible

Every parent’s situation is unique. Some may be fiercely independent and want to remain hands-off. Others might be relieved to delegate things like bill payments or appointment scheduling. The key is to agree on a shared plan that respects their wishes while also addressing practical concerns.

For some families, that might mean gradually taking on tasks like organizing bill payments, helping with taxes, or reviewing insurance coverage. For others, it could involve preparing for bigger decisions—like exploring home care options or moving to assisted living.

Try to balance compassion with clarity. It’s okay to say, “I want to make sure everything is in place now, so we don’t have to scramble later.” Helping your parents remain involved in decisions for as long as possible preserves their dignity and autonomy.

You can also revisit the plan as their needs evolve. A yearly check-in to review their financial documents, renew insurance policies, and update contact information is a great habit to adopt.

Use Tools and Resources to Lighten the Load

Managing someone else’s affairs can feel like a second job. Thankfully, there are tools that can help. Automatic bill payments and direct deposit can reduce the risk of missed due dates. Transaction monitoring services can flag suspicious activity and help prevent fraud. Some families use shared calendars or caregiver apps to stay on top of appointments and responsibilities.

Look into local and government resources too. Your province may offer programs that subsidize home care, equipment, or transportation. Some non-profits run adult day programs or offer respite services for caregivers.

If your parents have insurance—like long-term care coverage or disability insurance—review the policy now. Understanding what it does (and doesn’t) cover will help you avoid surprises later.

Moving Forward with Confidence

Caring for aging parents isn’t just about responding to emergencies—it’s about planning ahead so everyone feels supported, respected, and safe. By opening the lines of communication early, organizing important documents, and clarifying legal authority, you’ll be in a much better position to help when it’s needed most.

This stage of life can feel overwhelming, but you don’t have to go through it alone. Start by creating a simple checklist with your parents. Schedule a conversation this month—just one. Taking that small first step today can make a big difference tomorrow. We can help.

Disclaimer: This article is for informational purposes only and does not constitute financial, legal, or tax advice. Always consult a qualified professional regarding your specific situation. We are not responsible for any actions taken based on this content.

by Chris Geldert
Share this entry
  • Share on Facebook
  • Share on X
  • Share on WhatsApp
  • Share on Pinterest
  • Share on LinkedIn
  • Share on Tumblr
  • Share on Vk
  • Share on Reddit
  • Share by Mail
https://chrisgeldert.ca/wp-content/uploads/2025/11/supportingAgingParentsFI.png 700 1200 Chris Geldert https://chrisgeldert.ca/wp-content/uploads/2020/05/christopherGeldertLogo5.png Chris Geldert2025-11-03 07:26:472025-11-03 07:27:06Supporting Your Aging Parents Without Sacrificing Your Own Stability

Pages

  • ABOUT
  • ADVANTAGE ACCOUNT
  • BLOG
  • BUSINESS CONTINUATION
  • BUSINESS SUCCESSION
  • CONTACT
  • CRITICAL ILLNESS INSURANCE
  • CRITICAL ILLNESS INSURANCE
  • DISABILITY INSURANCE
  • DISABILITY INSURANCE
  • EMPLOYEE BENEFITS
  • ESTATE PLANNING
  • Estate Planning for Business Owners
  • Estate Planning for Retirees and Mature Families
  • Estate Planning for Young Families
  • EXECUTIVE BENEFITS
  • Families
  • Farms
  • FINANCIAL ADVICE
  • FINANCIAL ADVICE FOR BUSINESS OWNERS
  • FINANCIAL ADVICE FOR BUSINESS OWNERS
  • FINANCIAL ADVICE FOR SENIORS
  • FLEXCARE, ASSOCIATION, HEALTH AND DENTAL PLANS
  • GROUP BENEFITS
  • GROWING FAMILIES
  • GUARANTEED INVESTMENT CERTIFICATES
  • HOME
  • How will rising interest rates impact Canadians?
  • INDIVIDUAL HEALTH AND DENTAL PLANS
  • Insurance Planning
  • Insurance Planning for Business Owners
  • Insurance Planning for Young Families
  • INVESTMENT PLANNING
  • LATEST NEWS
  • LIFE INSURANCE
  • Life Insurance
  • LIFE STAGES
  • MATURE FAMILIES
  • Mortgage Insurance
  • MORTGAGE LIFE INSURANCE
  • Non Registered Investments
  • Planning for Seniors
  • Preparing for Retirement
  • PRIVACY STATEMENT AND WEBSITE TERMS OF USE
  • REGISTERED DISABILITY SAVINGS PLAN
  • REGISTERED DISABILITY SAVINGS PLAN
  • REGISTERED EDUCATION SAVINGS PLAN
  • REGISTERED EDUCATION SAVINGS PLAN
  • REGISTERED RETIREMENT INCOME FUND
  • REGISTERED RETIREMENT INCOME FUND
  • REGISTERED RETIREMENT SAVINGS PLAN
  • REGISTERED RETIREMENT SAVINGS PLAN
  • Resources
  • RETIREES
  • RETIREMENT PLANNING
  • Retirement Planning for Business Owners
  • Retirement Planning for Employees
  • SERVICES
  • STARTING YOUR CAREER
  • STRATEGIC PARTNERSHIPS
  • SUPPLIERS
  • SUPPLIERS-old
  • TAX FREE SAVING ACCOUNT
  • TAX FREE SAVING ACCOUNT
  • THE NEED FOR CORPORATE LIFE INSURANCE
  • The Need for Corporate Life Insurance
  • THE NEED FOR PERSONAL LIFE INSURANCE
  • The Need for Personal Life Insurance

Categories

  • 2020
  • 2020 Only
  • 2021
  • 2022
  • 2022 Only
  • 2023
  • 2024
  • 2025
  • 2026
  • Accountants
  • Blog
  • Budget
  • Business Owners
  • Business Owners
  • Business Succession
  • Business Succession Planning
  • Buy Sell
  • Center of Influences
  • Charitable Gifting
  • Coronavirus
  • Coronavirus – Associates
  • Coronavirus – Practice Owners
  • Coronavirus – Retired
  • Coronavirus – Retiring
  • Coronavirus – Students
  • corporate
  • Critical Illness Insurance
  • Debt
  • dental benefits
  • disability
  • Disability Insurance
  • Estate Planning
  • Family
  • farmers
  • Finance
  • financial advice
  • Financial Planning
  • Government Budget
  • Group Benefits
  • health benefits
  • incorporated professionals
  • individuals
  • Insurance
  • Investment
  • Life Insurance
  • long term care
  • mortgage
  • Ontario Only
  • pension plan
  • personal finances
  • Professional Corporations
  • Professionals
  • RDSP
  • Registered Education Savings Plan
  • Retirees
  • Retirement
  • RRSP
  • RRSP
  • tax
  • Tax Free Savings Account
  • Travel Insurance

Archive

  • October 2026
  • September 2026
  • August 2026
  • July 2026
  • June 2026
  • May 2026
  • April 2026
  • March 2026
  • February 2026
  • January 2026
  • December 2025
  • November 2025
  • October 2025
  • September 2025
  • August 2025
  • July 2025
  • June 2025
  • May 2025
  • April 2025
  • March 2025
  • February 2025
  • January 2025
  • December 2024
  • November 2024
  • October 2024
  • September 2024
  • August 2024
  • July 2024
  • June 2024
  • May 2024
  • April 2024
  • March 2024
  • February 2024
  • January 2024
  • December 2023
  • November 2023
  • October 2023
  • September 2023
  • August 2023
  • July 2023
  • June 2023
  • May 2023
  • April 2023
  • March 2023
  • February 2023
  • January 2023
  • December 2022
  • November 2022
  • October 2022
  • September 2022
  • August 2022
  • July 2022
  • June 2022
  • May 2022
  • April 2022
  • March 2022
  • February 2022
  • January 2022
  • December 2021
  • November 2021
  • October 2021
  • September 2021
  • August 2021
  • July 2021
  • June 2021
  • May 2021
  • April 2021
  • March 2021
  • February 2021
  • January 2021
  • December 2020
  • November 2020
  • October 2020
  • September 2020
  • August 2020
  • July 2020
  • June 2020
  • May 2020
  • April 2020

Chris Geldert CPA, CA, CLU, CEA

Navigating corporate structures and the insurance world can be difficult. I specialize in assisting business owners protect, realize and transfer the value of their business and corporate wealth. I guide owners through the process and work with their various professionals to ensure solutions implemented properly manage risks and maximize benefits. Above all, I work to earn your business.

Subscribe to my newsletter

* indicates required


Contact Me

Tel: (403) 620-8534

E: Cgeldert@shaw.ca

© 2020 Financial Tech Tools Inc. - Enfold WordPress Theme by Kriesi
Link to: Finding Coverage That Fits: Flexible Insurance Choices for Canadians Link to: Finding Coverage That Fits: Flexible Insurance Choices for Canadians Finding Coverage That Fits: Flexible Insurance Choices for Canadians Link to: Living Paycheque to Paycheque: How Canadians in the Gig Economy Can Build Financial Security Link to: Living Paycheque to Paycheque: How Canadians in the Gig Economy Can Build Financial Security Living Paycheque to Paycheque: How Canadians in the Gig Economy Can Build Financial...
Scroll to top Scroll to top Scroll to top